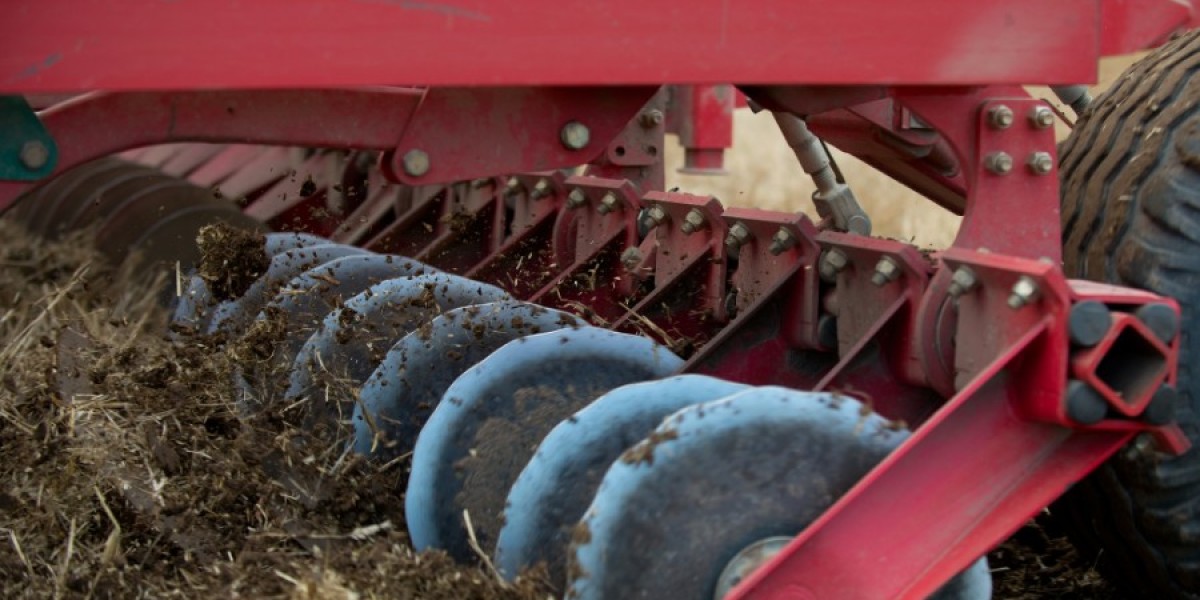
The agricultural equipment market encompasses the machinery and technologies used to prepare land, plant crops, manage fields, protect plants, harvest produce and process agricultural output. From tractors and harvesters to irrigation systems and precision spraying equipment, these technologies are becoming increasingly important as farmers seek higher productivity, better resource efficiency and lower dependence on manual labour.
The global agricultural equipment market reached USD 231.77 billion in 2025 and is projected to reach USD 543.67 billion by 2035, expanding at a CAGR of 8.90% during 2026–2035, based on the market figures supplied for this analysis.
The industry's importance extends beyond machinery sales. Agricultural equipment directly influences how efficiently land, water, seeds, fertilizers and labour are converted into food and other agricultural commodities. Mechanization can shorten planting and harvesting windows, improve operational consistency and allow farmers to manage larger areas.
At the same time, agricultural machinery is undergoing a technological transition. GPS guidance, telematics, automated steering, variable-rate application, machine learning, sensors and electric powertrains are gradually becoming part of modern farm operations. The result is an industry increasingly defined by the combination of mechanical engineering and digital agriculture.
Mechanization Is Reshaping Modern Farming
Agricultural mechanization improves farm productivity by replacing or augmenting manual tasks with machines that can operate over larger areas and within tighter seasonal windows. Its impact is particularly important where labour availability, farm size and climate variability make timely field operations difficult.
Tractors remain the foundation of agricultural mechanization because they provide the power and traction required for multiple implements. Modern tractors can support ploughing, tillage, planting, spraying and material handling, while increasingly sophisticated models integrate satellite navigation, automated steering and data connectivity.
The evolution from basic tractors to digitally connected machines is changing how farmers think about equipment purchases. A tractor is no longer simply a source of mechanical power. It can become a data-gathering and decision-support platform capable of communicating with implements, farm-management software and cloud-based systems.
Harvesters represent another critical segment. Combining harvesting, threshing and cleaning operations into a single machine can dramatically reduce the time required to bring crops from field to storage. This is particularly valuable for cereals and other crops where delays can increase the risk of weather-related losses.
Planting equipment is similarly important because seed placement influences crop establishment and ultimately yield potential. Precision planters can control seed spacing and depth while integrating information from field maps and soil conditions.
The broader market therefore reflects a shift toward timely, precise and data-supported mechanization, rather than simply increasing the number of machines available to farmers.
How Are Smaller Farms Influencing Equipment Design?
Smaller farms create demand for machinery that is affordable, compact, versatile and easy to maintain. Manufacturers are responding with smaller tractors, multi-purpose implements and equipment designed for fragmented fields.
This trend is especially relevant across parts of Asia and other emerging agricultural markets, where average farm sizes can be considerably smaller than those of large commercial farms in North America.
Equipment-sharing models can also improve access. Rather than purchasing expensive machinery individually, farmers can obtain services from custom operators or participate in machinery-sharing arrangements. This can make mechanization economically viable even when individual farm acreage is insufficient to justify ownership.
Product Segments Supporting the Agricultural Value Chain
Tractors, harvesters, planting equipment, irrigation and crop-processing machinery, spraying systems, and hay and forage equipment each address different stages of agricultural production. Together, they form an interconnected machinery ecosystem spanning field preparation through post-harvest processing.
Tractors account for a foundational role because their versatility makes them useful across diverse agricultural operations. Their specifications vary significantly, from compact machines suited to horticulture and small farms to high-horsepower tractors designed for large-scale field agriculture.
Harvesters are becoming increasingly sophisticated. Modern combine harvesters can monitor crop conditions, adjust harvesting parameters and collect operational data. Automation can help operators maintain machine performance as field conditions change.
Planting equipment is moving toward precision agriculture. Modern planters and seed drills can control placement more accurately while supporting variable-rate seeding strategies. This can help farmers respond to differences in soil characteristics and expected productivity across a field.
Irrigation and crop-processing equipment address two areas where resource efficiency is particularly important. Efficient irrigation systems can deliver water more precisely, while processing equipment helps transform harvested crops into marketable products.
Spraying equipment is also becoming more technology-intensive. Precision sprayers can use GPS mapping, sensors and increasingly sophisticated application controls to improve chemical placement and reduce unnecessary application.
Hay and forage equipment remains important for livestock agriculture. Mowers, balers, forage harvesters and related machinery help farmers efficiently produce and preserve feed.
The "others" category encompasses specialised equipment that does not fit neatly into these major groups, demonstrating the breadth of the agricultural machinery ecosystem.
Equipment Applications From Land Preparation to Processing
Agricultural equipment is used throughout the production cycle, beginning with land development and seed-bed preparation and continuing through planting, crop management, harvesting and post-harvest processing. Each stage presents different opportunities for mechanization and precision technology.
Land development and seed-bed preparation establish the physical conditions needed for successful crop establishment. Tractors and tillage implements can prepare soil, manage residues and create planting conditions, although modern conservation agriculture increasingly encourages farmers to minimise unnecessary soil disturbance.
During sowing and planting, equipment must place seeds accurately and consistently. Precision planting technology can help control spacing, depth and population, supporting more uniform crop emergence.
The weed cultivation stage includes mechanical weed management and field operations designed to control competing vegetation. While chemical herbicides remain widely used, advances in machine vision and robotics are opening possibilities for more targeted mechanical or precision weed control.
Plant protection encompasses spraying and other interventions against pests and diseases. This is an area where precision agriculture can create measurable value because over-application increases costs and environmental exposure, while under-application can compromise crop protection.
Harvesting and threshing represent perhaps the most time-sensitive stage. Farmers often have a narrow window in which crops must be harvested at suitable maturity and moisture levels. High-capacity machinery allows producers to cover more acreage before adverse weather or crop deterioration becomes a problem.
Post-harvest and agro-processing equipment extends mechanization beyond the field. Cleaning, drying, grading, sorting and processing can reduce losses and improve the quality and marketability of agricultural products.
Why Does Timeliness Matter as Much as Machine Capacity?
A machine's value is not determined only by how much work it can perform per hour. Its ability to complete operations at the correct agricultural window can have a major effect on farm economics.
For example, planting too late can reduce yield potential, while delayed harvesting can expose mature crops to rainfall, pests or shattering. Equipment that increases operational capacity can therefore protect revenue as well as reduce labour requirements.
Precision Agriculture Is Changing Equipment Economics
Precision agriculture is turning farm machinery into connected technology platforms. GPS guidance, telematics, sensors, automated steering and variable-rate controls allow machines to respond more intelligently to field conditions.
Traditional agricultural machinery generally performs a task according to mechanical settings established by the operator. Precision equipment can incorporate digital field maps and sensor data to vary its operation across different parts of a field.
Variable-rate application illustrates the concept clearly. Instead of applying the same amount of seed, fertilizer or crop-protection product everywhere, equipment can adjust rates according to soil characteristics, crop requirements or historical yield data.
Machine telematics adds another dimension. Equipment can transmit information about fuel consumption, operating hours, location, maintenance status and performance. For large agricultural operations, these data can help managers coordinate fleets and schedule maintenance.
Automation is also progressing. Auto-steering systems can maintain precise driving paths, reducing overlaps and improving field efficiency. More advanced systems can automate selected field operations, reducing operator workload.
The commercial significance is substantial because farmers increasingly evaluate machinery based on total operating economics, including fuel consumption, downtime, input savings, maintenance and productivity.
Electric and alternative-power technologies are another emerging area. Compact electric tractors and autonomous platforms may become increasingly useful for horticulture, indoor agriculture and specialised operations, although battery energy density, charging infrastructure and machine economics remain important constraints for large-scale field work.
Regional Market Trends Across Global Agriculture
North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa have distinct agricultural structures, creating different equipment requirements and adoption patterns.
North America is characterised by large commercial farms, high levels of mechanization and strong adoption of precision agriculture. High-horsepower tractors, combines, autonomous systems and connected machinery have significant relevance because equipment can operate across extensive areas.
The region also provides a strong environment for data-driven agriculture. Farmers and agribusinesses increasingly integrate machine data with farm-management platforms, allowing equipment performance to become part of broader operational decision-making.
Europe has a highly developed agricultural machinery industry but faces distinctive pressures around environmental sustainability, emissions, soil conservation and input efficiency. These factors are encouraging manufacturers to develop machinery capable of precision application, reduced soil compaction and more efficient power usage.
Asia Pacific offers substantial long-term growth potential because of its enormous agricultural base and ongoing mechanization. India, China, Japan and Southeast Asian economies have different farm structures, but all present opportunities for machinery suited to local crops and field conditions.
In India, mechanization is increasingly relevant to addressing labour availability and improving timeliness of farm operations. Compact tractors, harvesters, planting equipment and custom-hiring models can help extend machinery access beyond farmers who can afford full ownership.
Latin America is a major agricultural production region, particularly for soybeans, maize, sugarcane and other commodities. Large-scale farming supports demand for high-capacity tractors, planters, sprayers and harvesters, while precision technology can help optimise operations across extensive fields.
The Middle East and Africa offer opportunities shaped by irrigation requirements, agricultural modernization and efforts to improve productivity. Water-efficient irrigation equipment is particularly relevant in arid and water-stressed areas, while mechanization can help address labour constraints.
Regional differences mean manufacturers cannot rely on a single equipment strategy. Successful products must reflect farm size, crop type, terrain, financing conditions, infrastructure and local service availability.
Major Growth Drivers and Market Challenges
The agricultural equipment market is benefiting from rising food demand, labour shortages, farm mechanization, precision agriculture and the need to improve resource efficiency. However, high equipment costs, financing constraints, maintenance requirements and volatile farm incomes can limit adoption.
Population growth and changing diets continue to increase pressure on agricultural productivity. Farmers need to produce more output while managing finite land and water resources, creating a long-term need for efficient machinery.
Labour availability is another important driver. Seasonal agricultural work can be physically demanding, and many farming regions face migration from rural areas toward cities. Mechanization can help farmers complete critical operations when sufficient labour is unavailable.
Climate variability is strengthening the importance of timely operations. Farmers increasingly need machinery that can perform efficiently during unpredictable planting and harvesting windows.
At the same time, the purchase price of modern agricultural equipment can be substantial. Advanced tractors and harvesters incorporate electronics, hydraulics, software and precision systems that increase capability but can also increase acquisition and repair costs.
Financing is therefore central to market development. Farmers often evaluate machinery purchases based on expected productivity gains and cash flow rather than technical specifications alone.
After-sales service is equally important. A technologically advanced machine that cannot be repaired quickly during planting or harvest can create significant economic losses. Manufacturers with strong dealer networks, spare-parts availability and technician support have an important commercial advantage.
Competitive Landscape and Leading Manufacturers
The agricultural equipment industry is highly competitive and includes global manufacturers with extensive product portfolios, regional specialists and companies developing increasingly connected machinery. Competition is shifting from mechanical performance alone toward technology integration, reliability, service and total cost of ownership.
The companies covered in the market landscape include Deere & Company, CNH Industrial N.V., AGCO Corporation, Mahindra & Mahindra Ltd., and Kubota Corporation, alongside ISEKI & CO., LTD. and other market participants.
Deere & Company has developed a broad portfolio spanning tractors, harvesters, planting equipment and precision agriculture technologies. Its strategy illustrates how equipment manufacturers are expanding into software, connectivity and automated operations.
CNH Industrial N.V. participates through brands and technologies covering tractors, harvesting equipment and agricultural systems. Its competitive position reflects the importance of offering machinery across multiple farm operations.
AGCO Corporation has a broad agricultural equipment portfolio and focuses on precision agriculture alongside conventional machinery. Its business demonstrates how manufacturers increasingly combine machinery with digital farm-management capabilities.
Mahindra & Mahindra Ltd. has a particularly strong connection to emerging-market mechanization and tractor demand. Its position reflects the importance of compact and mid-range equipment in markets where small and medium-sized farms are widespread.
Kubota Corporation has established a broad presence in tractors, agricultural machinery and compact equipment. Its product strategy illustrates the importance of matching machine size and capability with diverse farming conditions.
ISEKI & CO., LTD. is another established participant, particularly associated with tractors and specialised agricultural machinery.
Competition is increasingly centred on ecosystems. Manufacturers are developing connected machines, precision software, autonomous capabilities and financing or service offerings alongside traditional equipment.
The Shift Toward Autonomous and Sustainable Farm Machinery
Autonomous equipment, robotics, electrification and artificial intelligence are likely to shape the next phase of agricultural machinery development. These technologies can reduce labour requirements while allowing machines to operate more precisely and continuously.
Autonomous tractors are among the most visible emerging technologies. Rather than eliminating the operator from every agricultural task immediately, manufacturers are developing systems that automate navigation and selected field operations while retaining human oversight.
Robotics is particularly promising for specialised crops. Machine vision can help identify weeds, fruits or plant conditions, allowing robots to perform targeted tasks that would otherwise require considerable manual labour.
Artificial intelligence can also improve machinery performance by interpreting data from cameras, sensors and field-management systems. In harvesting, for example, machine intelligence can potentially adjust operating parameters according to crop conditions.
Sustainability is another major development area. More precise equipment can reduce overlapping applications and unnecessary input use. Improved engine efficiency, alternative powertrains and reduced soil compaction can further lower the environmental footprint of farming operations.
However, adoption will depend on economics. Farmers need technology that is sufficiently reliable and affordable to justify the investment. Complex systems must also be easy to operate and supported by dependable service networks.
Agricultural Equipment Market Outlook Through 2035
The agricultural equipment market is moving toward a more connected, automated and precision-oriented future. Traditional machinery such as tractors and harvesters will remain essential, but their capabilities will increasingly be enhanced by sensors, software, connectivity and automation.
Based on the market figures supplied for this analysis, the industry is expected to expand from USD 231.77 billion in 2025 to USD 543.67 billion by 2035, representing a CAGR of 8.90% during 2026–2035.
Growth will be supported by mechanization in emerging agricultural markets, replacement demand in mature economies, labour constraints and the increasing need to improve resource efficiency. Precision technologies can strengthen the value proposition by helping farmers optimise seed, fertilizer, water and crop-protection inputs.
Regional dynamics will remain important. North America and Europe are likely to continue emphasizing high-capacity, connected and automated equipment, while Asia Pacific and other developing agricultural markets will generate demand across a wider range of equipment sizes and price points.
The competitive landscape will also continue to evolve. Companies that combine reliable mechanical platforms with digital services, autonomous technologies and strong after-sales networks can address a broader share of the farm's operational needs.
Ultimately, agricultural equipment is becoming more than a collection of machines. It is becoming part of a connected production system in which mechanical power, agronomic data and automation work together. The manufacturers that successfully make advanced technology practical, serviceable and economically compelling for farmers will help define the next stage of global agricultural mechanization.